Experian®
- 722.08K
- 4.7
- Installs
- 10.00M
- Price
- Free
Screenshots
Analysis by Reviewed APKs
Experian is a finance app for checking your credit information, viewing a FICO Score, and exploring services tied to your financial profile. I see it as a useful home base for people who want to keep an eye on their credit and understand possible next steps, without making a spreadsheet of every detail. Its free tools are the main draw, though some extras belong to paid membership.
A quick credit check
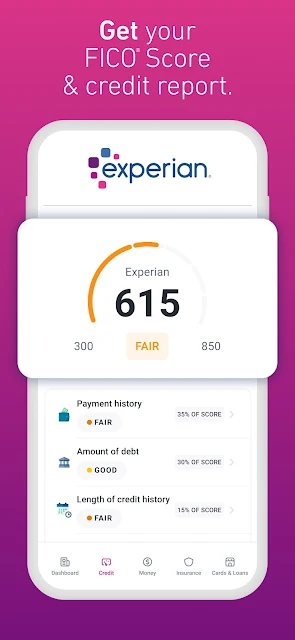
When I first opened Experian, I pictured using it during one of those ordinary moments when a money question pops up: before applying for a card, after paying a few bills, or while checking whether anything new has appeared on my credit file. The app brings together a credit report, a FICO Score, monitoring, and suggestions, so the starting point is less scattered than switching between separate services.
For example, I could make a brief monthly check-in part of my routine: review the report and score, notice whether the app has flagged a new account or inquiry, then consider whether any suggested action is relevant. Experian also offers a financial health assessment and a marketplace for comparing selected financial offers. Those tools give a credit check more context, although they are prompts to explore, not decisions made for me.
A credit toolkit, not a bank
Experian is best understood as a credit and financial-services companion rather than an all-purpose banking app. Its center of gravity is the Experian credit report and FICO Score, with monitoring and products linked to that profile. If my main task were tracking every purchase, managing a budget, or seeing balances across bank accounts, the description does not position this app as a replacement for tools focused on those jobs.
Compared with checking a credit report only when a lender asks for one, an app can make occasional review feel more approachable. The trade-off is that the app’s information centers on Experian, and its description notes that lenders and insurers may use a different score or credit file. I would treat its score as one useful reference, not as a universal answer about every lender’s view.
Make check-ins deliberate
A little structure helps keep a credit app useful without turning it into something I check constantly. I’d choose a regular day to review the report and monitoring notices, then make a note of questions to follow up on. If a new inquiry or account appears, the app’s alert can prompt a closer look; the important habit is reading the details rather than reacting to a notification in isolation.
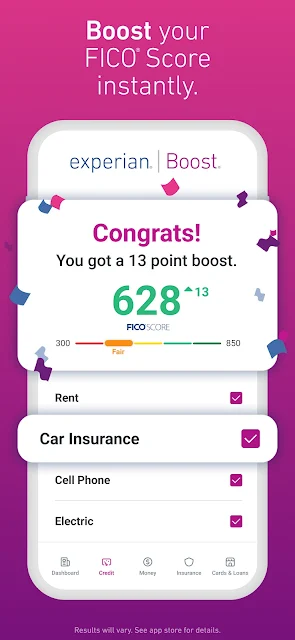
Experian Boost is another feature to approach thoughtfully. It can use eligible payments such as cell phone, utility, streaming, and rent payments in an effort to raise a FICO Score, but not every payment qualifies and results vary. I’d review the terms and decide whether connecting eligible payment information suits my preferences. The app makes the option visible; it does not make the choice for me.
More From Our News Desk

Zoom Meetings, Google Meet, or Teams: Which Is Easiest to Join?

How I Build a Free Streaming Lineup With Tubi

Why Crunchyroll Is the Default Anime App for So Many Fans

YouTube TV: A Practical Guide to Cutting Cable

Rummikub and the Small Comfort of Phone Games

TeamViewer Remote Control or AnyDesk for Helping Family?
Who may find it useful
I’d recommend Experian to someone who wants a convenient place to view an Experian credit report and FICO Score, keep watch for new accounts or inquiries, and browse credit-profile-based offers. The free membership gives the app a practical starting point, while tools such as Experian Boost may interest people who want to see whether eligible bills can contribute to their score. It suits a periodic check-in more than a full financial dashboard.
It may be a weaker fit for anyone looking for detailed spending plans, broad account aggregation, or a single score that represents how every lender evaluates them. Some advertised services are premium, and the app’s own notes say outcomes can vary. I’d also suggest that anyone uncomfortable sharing payment information take time to consider the Boost terms before connecting accounts. The useful approach is to choose only the features that match your needs.
Experian is the developer. On Google Play, Experian has more than 10 million installs and a 4.7-star rating from around 722,000 ratings. The app is free to download, and Google Play lists it as containing no ads and offering no in-app purchases. Its content rating is Everyone.
The current version is 4.2.36. Experian was released on May 12, 2016, and its last update was October 21, 2026. The minimum Android version is worth checking on Google Play, since that requirement can depend on the device and the current app release.
How Experian Fits a Credit Routine
A focused first look
My first impression is that Experian has a clear central purpose: put credit information and related services in one app. The free membership offers access to an Experian credit report and FICO Score without requiring a credit card, according to the description. That makes it easier to begin with the basics before deciding whether any additional service is worth exploring.
The app’s range also means it helps to be selective. Credit monitoring, Boost, a marketplace, and a financial health assessment all sit beside the core report and score. I’d start by finding the information I came for, then explore the other tools one at a time. That keeps the experience grounded in a real question instead of letting a long list of financial options become the task.
A steady day-to-day check
For everyday use, the most practical loop is simple: check the report and score when needed, then pay attention to monitoring notices about accounts opened in your name or new inquiries on the Experian report. That kind of review can help me notice a change worth investigating. It is still a prompt to verify details, rather than a substitute for understanding what is happening with an account.
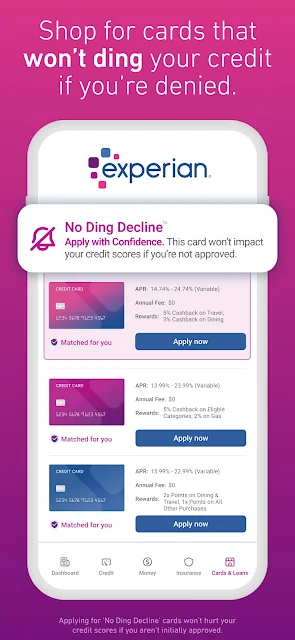
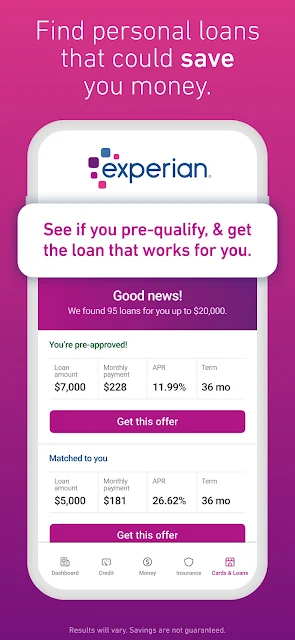
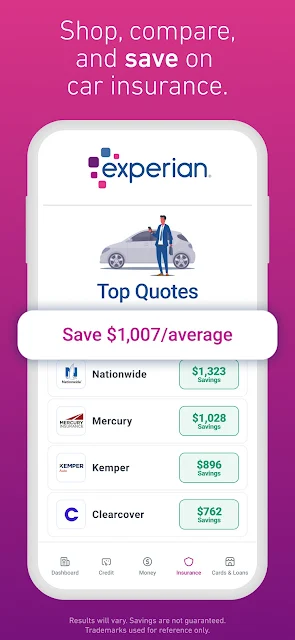
Experian also presents credit-card, personal-loan, and car-insurance offers matched to a credit profile. I’d use that marketplace when I’m actively comparing options, not as a reason to apply for something on impulse. The app notes that approval is not assured and that offers may not be available in every state. Those limits make it sensible to read offer details and terms before taking another step.
Features with a clear purpose
Experian Boost is one of the more distinctive tools in the free membership. It lets users connect eligible payments—including certain phone, utility, streaming, and rent payments—for possible impact on a FICO Score. The description is careful that eligibility and results vary. I appreciate that distinction: the feature may be relevant to some people, but it should not be treated as a promised score increase.
Credit monitoring is another central feature, with notices about accounts opened in a user’s name or new inquiries on the Experian report. The financial health assessment takes a different angle: it uses a survey to suggest possible actions for overall financial health and is informational, not professional advice. Together, these features cover both watching for changes and thinking through possible next steps.
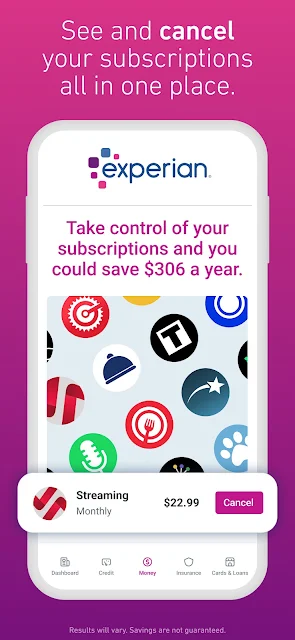
There are also paid-membership benefits, including bill negotiation and subscription cancellation, plus Experian CreditLock. The description says CreditLock is separate from a security freeze, so I would not treat those as interchangeable. Experian Cash, powered by Brigit, is described as a possible advance for eligible users. These are distinct services with their own conditions, rather than automatic parts of the free credit check.
A monthly review routine
A useful routine could be to set aside a few minutes once a month to review the Experian report, score, and any monitoring notices. If something looks unfamiliar, I’d first read the information carefully and work out what the notice refers to. Keeping the check-in on a calendar can make it easier to remember without needing to open the app every day.
A separate review makes sense before comparing products. I’d look at marketplace offers only when I have a particular kind of card, loan, or insurance quote in mind, and I’d read the offer conditions rather than assuming a match means approval. If I’m curious about Boost, I’d consider eligible payments and the account-connection terms on their own merits instead of treating it as a required step.
For premium features, I’d check the membership terms before relying on bill negotiation, cancellation, CreditLock, or an advance. The description says some services require paid membership, that eligibility varies, and that express delivery for an advance may involve a fee. A deliberate review helps separate the free credit tools from optional services with additional conditions.
Keep the boundaries in view
The biggest limitation is that Experian’s credit information is not necessarily the whole picture. Its description notes that a lender or insurer may use another score or credit file, and that not every lender uses scores affected by Boost. A score shown in the app can be informative, but it may differ from the number used in a particular application.
Several features have qualifications that matter in everyday use. Boost applies only to eligible payments and may not improve a score. Marketplace offers are not available everywhere, and approval is not assured. The financial health assessment is informational rather than individualized professional advice. Reading those caveats is part of using the app sensibly, especially when an offer or score change could influence a decision.
Finally, Experian combines free access with paid membership benefits, so the word free should not be taken to mean every service has the same terms. Bill negotiation and subscription cancellation require a paid membership and connected payment accounts, according to the description. Cash eligibility and delivery options vary as well. I’d check the terms for any feature before signing up or connecting information.
Experian makes sense as a convenient place to check an Experian credit report and FICO Score, keep an eye on certain changes, and explore related tools. I like that the free membership offers a useful starting point, while the app explains that Boost, marketplace offers, and premium services have limits and conditions.
I’d recommend it to people who want a periodic credit check-in and are comfortable reviewing options carefully. I would not choose it as a substitute for a budgeting or banking app, or assume its score represents every lender’s view. Used for its specific strengths, it can be a practical addition to a financial routine.
Experian Frequently Asked Questions
What is Experian used for?
Experian is used to view an Experian credit report and FICO Score, monitor certain changes on the Experian report, and explore tools such as Boost, a financial health assessment, and matched financial offers. Some other services, including bill negotiation and CreditLock, are described as premium benefits. What is available and useful can depend on eligibility and the service terms.
Which devices and platforms support Experian?
Experian is an Android app available through Google Play. The provided app information does not give a minimum Android version, so check the Google Play store page for the current device requirement. Compatibility can vary by device and app release, so it is sensible to check the store before installing.
Does Experian cost money?
Experian is free to download, and its description says users can get a free membership for a credit report and FICO Score. The app’s Google Play information lists no in-app purchases, while the description also refers to paid membership benefits and fees that may apply to some services. Check the store and service terms for current details.
Can Experian improve my credit score?
Experian Boost can include eligible bill payments in an effort to raise a FICO Score, but not all payments qualify and results vary. The app also provides credit monitoring and a financial health assessment. No particular score change is assured, and the score shown may differ from one used by a lender or insurer.
Who is Experian best suited to?
Experian may suit people who want to review an Experian credit report and FICO Score, watch for certain report changes, or compare selected financial offers. It may be less suitable as a replacement for a budgeting or banking app, or for someone who wants one score to represent every lender’s assessment. Feature eligibility and terms can vary, so check the store and service details.
Pros
- Free membership includes access to an Experian credit report and FICO Score.
- Monitoring can flag new accounts or inquiries on the Experian report.
- Boost can consider eligible phone, utility, streaming, and rent payments.
- Marketplace and assessment add options beyond simply viewing a score.
Cons
- Boost eligibility and score results vary, and not every bill qualifies.
- Some services require paid membership or have additional conditions.
- The Experian score may differ from scores used by lenders or insurers.
- Category
- Finance
- Version
- 4.2.36











